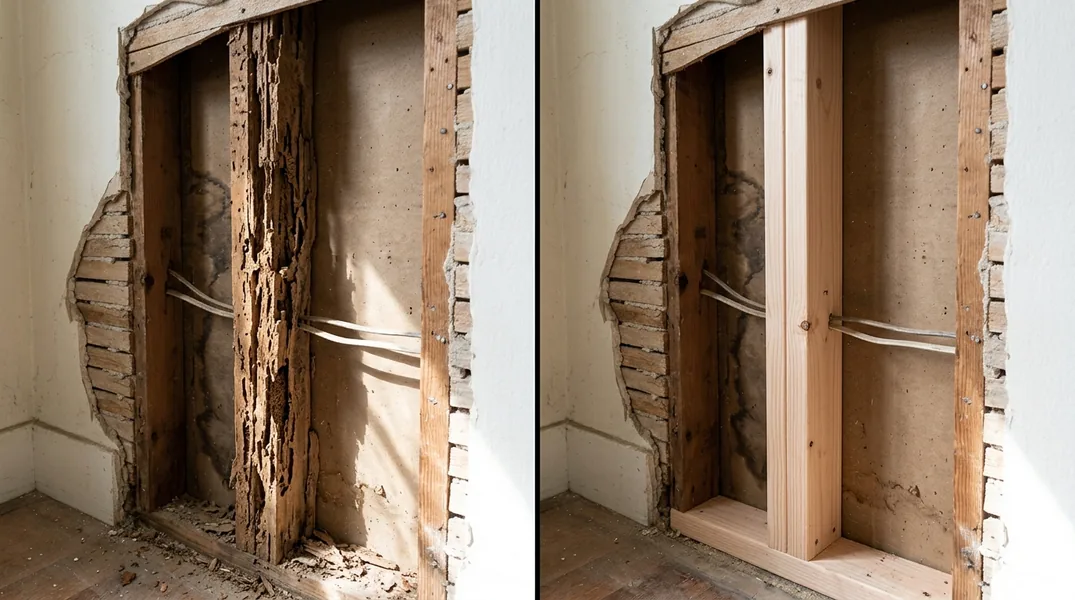
Does Homeowners Insurance Cover Wood Rot and Dry Rot?
One of the most common questions homeowners in Long Beach ask is whether their homeowners insurance will cover wood rot damage. The answer is rarely straightforward, and it depends heavily on what caused the rot in the first place.
Standard homeowners insurance policies typically do not cover wood rot that results from poor maintenance, age, or gradual moisture exposure. Insurance companies view this as a preventable condition that falls under the homeowner's responsibility to maintain. However, if wood rot develops as a direct result of a covered peril, such as a burst pipe, sudden storm damage, or fire, your policy may cover the resulting damage. The key distinction is whether the damage stems from a sudden, accidental event or from neglect over time.
When you file a claim for Wood Rot & Dry Rot Repair, your insurance adjuster will investigate the root cause. They'll look for evidence of how long the moisture problem has existed and whether you took reasonable steps to prevent it. If they determine the rot is due to a maintenance issue rather than a covered event, your claim will likely be denied. This is why it's essential to address moisture problems quickly and document your maintenance efforts.
Termite Damage Insurance: What's Actually Covered
Termite damage is another area where homeowners often face disappointment with their insurance coverage. Most standard homeowners insurance policies explicitly exclude damage caused by insects, including termites. This exclusion exists because termite infestations are typically considered a maintenance and prevention issue rather than a sudden, unexpected loss.
Insurance companies reason that homeowners can prevent termite damage through regular inspections, proper ventilation, and pest control measures. Since termite damage develops over time and is theoretically preventable, it falls outside the scope of typical coverage. If you've discovered termite damage in your Long Beach home, you'll likely need to cover the cost of Termite Damage Repair out of pocket.
Some specialized pest damage insurance riders exist, but they're not included in standard policies. If termite protection is important to you, contact your insurance agent about whether additional coverage is available. In the meantime, focus on prevention through regular inspections and professional pest control treatments. Early detection of termites can save you thousands in repair costs down the road.
Storm Damage Insurance Claims in Long Beach: What You Need to Know
Storm damage is one area where homeowners insurance typically provides more robust coverage. If high winds, heavy rain, hail, or lightning damage your home's structure, roof, or siding, your policy will usually cover the repairs. Long Beach experiences occasional severe weather, and when storms strike, knowing how to file a claim quickly can make a significant difference.
When filing a storm damage insurance claim, document everything with photos and written descriptions. Note the date and time of the storm, the specific areas affected, and any visible damage. Contact your insurance company promptly, as many policies have time limits for filing claims. Your insurer will send an adjuster to assess the damage and determine the payout amount. Be thorough in your documentation because this evidence supports your claim and helps ensure you receive fair compensation.
One important consideration is your deductible. Most homeowners insurance policies include a deductible that applies to storm damage claims, often ranging from $500 to $2,500 or even a percentage of your home's insured value. You'll be responsible for paying this amount before insurance coverage kicks in. Additionally, some insurers may offer a lower deductible for specific perils like wind or hail, so review your policy carefully to understand your obligations.
The Role of Maintenance in Insurance Coverage Decisions
Insurance companies make coverage decisions based partly on whether you've maintained your home reasonably. This principle applies to water damage, wood rot, and structural issues. If an adjuster determines that you failed to maintain your property, they may deny your claim entirely or reduce the payout. For example, if your roof was in poor condition and rain damage occurred, the insurer might argue that proper maintenance would have prevented the loss.
To protect your insurance coverage, keep detailed records of all maintenance work, repairs, and inspections. Document roof inspections, gutter cleaning, plumbing repairs, and pest control treatments. Take photos of your home's condition regularly, especially after performing maintenance. If you discover wood rot, moisture damage, or pest issues, address them immediately and keep receipts and contractor reports. This documentation demonstrates that you've taken reasonable steps to maintain your property, which strengthens your position if you need to file a claim.
Regular professional inspections also help identify problems early before they escalate into major, uncovered damage. Many contractors, including those offering Floor Joist & Subfloor Repair services, can identify moisture issues and wood damage during routine assessments. Catching these problems early often means the difference between a covered claim and an out-of-pocket expense.
When to Contact a Professional for Damage Assessment
If you suspect wood rot, termite damage, or storm damage in your home, getting a professional assessment is crucial before filing an insurance claim. A qualified carpenter or structural inspector can determine the cause and extent of damage, which directly impacts whether your insurance will cover repairs. Some damage may appear minor on the surface but involve significant structural issues underneath, while other visible damage might be cosmetic and not covered.
Long Beach Carpentry specializes in identifying and documenting structural damage, which can be invaluable when working with your insurance adjuster. A professional assessment provides objective evidence of the damage's cause and scope. If the damage stems from a covered peril, a contractor's report strengthens your claim. If it's due to maintenance issues, you'll at least know what needs to be repaired and can get accurate pricing for the work. Don't delay in getting this assessment, as evidence of the damage condition at the time of discovery is important for insurance purposes.
Whether you're dealing with water damage, wood rot, or structural concerns, reaching out for a free estimate helps you understand your next steps. Call Long Beach Carpentry at (562) 418-6699 to schedule an inspection and get professional guidance on your specific situation.
Protecting Your Home and Your Coverage Going Forward
Understanding your homeowners insurance coverage is only half the battle. The other half is taking proactive steps to prevent damage and maintain your property. Regular maintenance, prompt repairs, and professional inspections are your best defense against costly out-of-pocket expenses. Focus on controlling moisture in your home through proper ventilation, maintaining gutters and downspouts, and addressing plumbing leaks immediately. These steps prevent wood rot, reduce mold risk, and protect your structural integrity.
Additionally, review your insurance policy annually to ensure your coverage limits are adequate for your home's value and your area's risks. If you live in a region prone to specific hazards, such as coastal flooding in Long Beach, ask your agent about specialized coverage options. Keep your policy documents accessible and understand what is and isn't covered. When in doubt, ask your insurer directly whether a specific type of damage would be covered before a problem occurs.
Finally, establish a relationship with a trusted local contractor who can help you identify and address structural issues early. Whether you need Beam Replacement & Load-Bearing Wall Removal or routine inspections, having a professional in your corner ensures that damage is properly documented and addressed. Long Beach Carpentry is here to help with assessments, repairs, and the documentation you need for insurance purposes. Contact us at (562) 418-6699 or visit our website to learn more about how we can protect your home.
Looking for a professional carpentry contractor in Long Beach? Long Beach Carpentry responds fast for all your carpentry needs.
Get a Free QuoteOur services: Wood Rot & Dry Rot Repair · Termite Damage Repair · Floor Joist & Subfloor Repair